Maverick Protocol
Maverick Protocol Fees: What Determines LP Earnings and Real APR
Liquidity providers often enter DeFi with one goal: earn fees. But “fees” and “APR” are not the same thing, and the gap between them is where most LP disappointment happens. Real LP earnings depend on market conditions, liquidity utilization, and how your position behaves as price moves—not just on whatever number is shown on a dashboard. If you want to understand how the protocol frames liquidity behavior and fee mechanics, start with Maverick Protocol.
This guide explains what determines LP earnings and “real APR” on Maverick Protocol in a clear, beginner-friendly way. It follows EEAT principles by emphasizing transparent trade-offs, practical measurement, and risk awareness rather than hype.
What “Fees” Really Mean for LPs
When traders swap through a pool, they pay fees. Those fees are distributed to liquidity providers according to the pool’s rules and how much of their liquidity was actually used during swaps.
A simple reality check:
If your liquidity is not active near the trading price, it may earn little—even if the pool itself has high volume.
If your liquidity is active and frequently hit by swaps, fee earnings can look strong—until volatility changes your exposure.
The three components of LP outcomes
Your final result is usually driven by:
fee revenue
changes in token balances (exposure drift)
the market price movement of the underlying assets
APR becomes “real” only when you consider all three at once.
Maverick Protocol Fees: The Big Drivers of LP Earnings
Maverick Protocol is often discussed as a dynamic-liquidity AMM, where liquidity placement and behavior can influence how often your liquidity stays relevant near the active price. That matters for fees because it affects utilization.
In the middle of your research, it helps to review the protocol’s interface and documentation flow at Maverick Protocol to understand how positions are structured and how fee metrics are displayed.
The biggest factors that determine fees
Here are the drivers that matter most in practice:
Trading volume
- more swaps generally mean more fees
Fee tier / pool fee rate
- higher fee rates can increase revenue per trade (but may affect routing preference)
Liquidity depth near active price
- deeper liquidity near spot often improves execution and can attract more flow
Your liquidity utilization
- how often your liquidity is actually used in swaps
Volatility regime
- volatility can increase volume and fees, but also changes exposure more quickly
Competition from other LPs
- more liquidity can dilute your share of fee flow
The key metric most beginners miss: utilization
Two LPs can deposit the same value into the same pool and get different outcomes depending on:
how their liquidity is positioned
whether it stays active near price
how price moves during the period
Utilization is the bridge between “pool volume” and “my fees.”
Why Displayed APR Can Be Misleading
Dashboard APRs are usually estimates, not guarantees. They often rely on recent historical data and assumptions that can change instantly.
Common reasons displayed APR diverges from reality:
volume spikes that don’t persist
incentives included in APR that are temporary
changes in volatility that alter how active your liquidity remains
pool inflows that dilute returns
short measurement windows that exaggerate returns
A practical way to treat APR
Use APR as:
- a rough signal for recent activity
Do not use APR as:
- a promise of what you will earn next week
If you want a broader market-level perspective on why yield numbers can mislead in crypto (and how narratives form around “high APR”), mainstream coverage can provide helpful context: https://www.forbes.com/
The Hidden Variable: Exposure Drift vs Fee Income
Even if your fees look good, your net outcome can still be negative if your position’s exposure changes in an unfavorable way during price movement.
What “exposure drift” means in plain English
As swaps occur and price moves:
your position may end up holding more of one token and less of the other
the value of that mix may underperform simply holding the tokens
This is why “real APR” should always be measured against a baseline:
- “What if I just held token A and token B in the same ratio?”
The beginner baseline comparison
To estimate whether fees truly compensated you, compare:
LP position value today
vsvalue of holding the original deposited tokens today
If LP value is higher, fees plus position behavior helped.
If LP value is lower, fees did not compensate for exposure drift and market moves.
Maverick Protocol and Fee Quality: Not All Volume Is Equal
Some volume is healthier than other volume. For LPs, “good” volume is volume that pays fees without overwhelming you with adverse conditions.
Types of volume and how they affect LPs
Organic swap flow
- users actually swapping for real reasons
Arbitrage flow
- can be constant, but may be more “toxic” depending on timing and volatility
Incentive-driven churn
- can inflate metrics without producing sustainable fee demand
A pool with sustainable organic usage can sometimes be better than a pool with brief explosive volume.
How to Calculate “Real APR” Without Fooling Yourself
You don’t need complex spreadsheets to be honest about performance, but you do need consistency.
Step-by-step “real APR” method
Record your starting position:
date/time
amounts of token A and token B
USD value at deposit time (or your base currency)
Track fees earned over the period:
- note whether they auto-compound or require claiming
Record ending position value:
- total value of the LP position at the end date
Build the holding baseline:
- value today of the original token amounts
Compare outcomes:
- LP value minus holding value = net strategy benefit (or cost)
What to report (simple and useful)
period length (e.g., 14 days)
fees earned (in USD terms)
LP ending value
holding ending value
difference (LP minus holding)
This tells you more than any headline APR.
Maverick Protocol Risk Notes That Affect Earnings
EEAT-aligned guidance must include risks that directly impact fee outcomes.
Risks that can reduce or distort earnings
Smart contract risk
Market regime flips
- range-bound to trending, or calm to chaotic
Liquidity dilution
- new LPs entering reduces your share
MEV and execution dynamics
- can change flow patterns and outcomes for both traders and LPs
Gas costs
- can eat into returns if you claim/reposition frequently
If you want a solid foundation on transaction mechanics, gas, and why network behavior impacts strategy profitability, Ethereum’s official resources are helpful: https://ethereum.org/
Maverick Protocol Fee Optimization: Practical Strategies
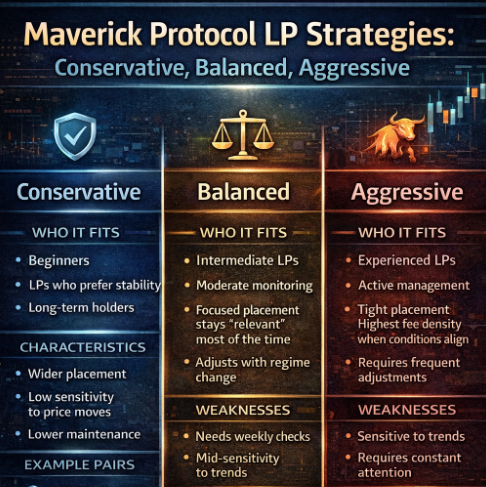
These are not “guaranteed profit tricks.” They’re common-sense habits that improve the odds your fees translate into real gains.
Fee optimization habits
Choose pools with consistent volume, not one-day spikes
Prefer strategies you can monitor at the level they require
Reassess when the market regime changes
Avoid over-tight setups if you can’t adjust quickly
Consider splitting capital:
a conservative core
a smaller opportunistic position
A simple “best practice” monitoring routine
Daily (optional):
- check whether fees are accruing and whether utilization seems healthy
Weekly (recommended):
compare LP value vs holding value
check whether pool liquidity grew (dilution risk)
reassess volatility and regime
Monthly:
- decide if the strategy still fits your time and risk tolerance
Before you scale up or change strategies, revisit the official position and fee presentation on Maverick Protocol so you understand exactly how fees accrue and what your position is designed to do as price moves.
Real APR is not a number you find—it’s a number you measure. The best LPs treat fee income as one part of the outcome and constantly compare against the simplest baseline: holding. If your strategy beats holding after fees, exposure drift, and costs, then you’ve earned real APR. If it doesn’t, you didn’t fail—you learned what the market regime demanded.